This category is about all aspects of Holiday Home Insurance and will be of interest to owners of holiday homes, cottages and holiday complexes across the UK. As Holiday Home Insurance Specialists Boshers are experts and provide tips and guidance. Check out these posts, Holiday Homes – getting your Buildings Insurance Right, Dog Friendly Holiday Home Insurance, How much should your holiday home insurance cost?, Frequently asked holiday home insurance questions, Getting your Holiday Let Insurance Right – Public and Employers Liability

public and employers liability insurance

public and employers liability insurance

Every holiday home is different, so making sure you have the right insurance in place for your holiday let property is incredibly important. You may think that a standard home insurance policy will do the job, but when guests are paying to stay in your holiday let , the Public and Employers Liability Insurance from basic home insurance won’t cover you. Nor will it if you have any employees (cleaners, gardeners, seasonal staff etc.).

Whilst we understand that you do your best to keep your guests and employees safe, we know that accidents can, and do, happen. If someone does get hurt whilst staying at your holiday let having the right insurance can save you a lot of time, money, and stress.

In this post, we take a look at Public Liability Insurance and Employer’s Liability Insurance.

Why are Public Liability Insurance and Employer’s Liability Insurance important?

Public Liability Insurance covers the legal liability of the policyholder for bodily injury, death, disease or illness. This means that should anything happen to your guests, you won’t be having to empty your pockets in legal or settlement fees. Whether there’s been a slip that resulted in a bumped head, or a far worse accident, Public Liability Insurance will keep your holiday let protected from legal costs and any compensation that may occur.

This works alongside Employer’s Liability Insurance, protecting you from the cost of compensation claims. If an employee claims to have an illness or injury from working for you, the bills will be taken care of.

You will be classed as an employer if you have a contract of service with anyone who helps you maintain your holiday let, whether spoken, written, or implied. This includes cleaners, gardeners, seasonal staff, and even volunteers.

Are Public and Employers Liability insurance necessary?

Employer’s Liability Insurance is a legal requirement, regardless of whether you have a cleaner once a month or once a week, you need to have the right insurance. Even if your workers are only seasonal, comprehensive cover is still a necessity.

The Health and Safety Executive (HSE) enforces the requirement, and you could be fined at a rate of £2,500 for every day you have traded without Employer’s Liability Insurance.

The minimum legal requirement for Employer’s Liability Insurance is £5million, but in practice many insurers (including us) provide cover of £10million.

Whilst Public Liability Insurance is not a legal requirement, it is good business practice. You can keep your holiday let as secure and safe as you like, but if that one wobbly paving stone trips a guest up, or the path covered with wet leaves causes a slip, you could be facing some big fees.

With so many guests visiting your holiday let each year, not having Public Liability Insurance is a big risk to take. It is particularly important that this insurance is for holiday homes, as standard Public Liability Insurance will not cover you and your let.

How much cover do I get?

It is recommended that holiday let homeowners get Employer’s Liability Insurance coverage for £10million, and Public Liability Insurance of at least £5million for smaller properties (sleeping up to two guests) and £10million for larger properties.

Our Specialist Holiday Home Insurance Policy provides Employer’s Liability Insurance of £10million and Public Liability Insurance of £10million as standard.

Boshers offer specialist holiday home insurance to owners across the UK. For more information on how a specialist insurer can help and support your holiday home business, please give us a call on 01237 429444.

For further information on UK holiday home insurance visit the website page most relevant to you:

Modern Living Room Holida Home Contents Insurance

Modern Living Room Holida Home Contents Insurance How much are the contents currently in your property worth if you had to replace them like for like as new? Whether it’s your own home insurance or your holiday home contents insurance, it’s a question we’ve all faced from time to time when seeking a quote. It’s an important question too; go too low and should the worst happen you’ll potentially find yourself short or underinsured. Go too high and you’ll be over insured, paying an unnecessarily high premium year after year.

So how many of us really know the true value of the possessions in our holiday homes?

Is it £25,000? £35,000? Or even more?

Have you considered the soft furnishings, curtains and the carpets? They count too, as do the gadgets, furniture and even the clock hanging from the wall or the ornaments adorning the bedside tables.

Still think you know? If not, here’s our helpful overview to make sure you’re ticking off every item and making an informed decision on the level of cover you really need.

Account for the full replacement cost as new for holiday home contents insurance purposes

You may have queued up from 0600 in the morning on New Years day to furnish your holiday home in the sales at bargain prices but when your three piece suite is damaged beyond repair in mid-summer you’ll want a like for like replacement quickly and without question. For this reason it is important to insure for the full cost as new for all of your holiday home contents, that’s the full retail price without discounts.     

Electrical Equipment

One of the biggest growth areas in contents is the sheer volume of gadgets we all have in our homes, and holiday cottages are no exception. Make a list of the items you have including some of the following:

  • Televisions, DVD players and other entertainment systems such as PlayStation’s or an Xbox
  • White goods including your freestanding oven, microwave, dishwasher, fridge freezer, washing machine and tumble drier.
  • Remember your cleaning equipment also counts, so add that shiny Dyson or humble Hettie the Hoover in there too!

Your furniture

The furniture throughout your holiday home will add up to a considerable cost should it need to be replaced. Go through each room and make note of all of the furniture and furnishings and other contents in each, not forgetting to open the drawers and cupboards where spare bedding, linen or towels may be stored:

  • Your sofas are likely to be the key item in the living room; don’t forget to include any soft furnishings you’ve added to them too such as scatter cushions.
  • When it comes to bedrooms and your beds you’re going to want to include both the frame and the mattress (even the pillows and the bedding too), which can be expensive should they need to be replaced.
  • Where do your guests enjoy an evening meal? If it’s at a dining table and chairs be sure to add this to the list.
  • Those kitchen utensils, pots, pans, dinner service and cutlery they’re making and eating their meal with? You’ve got it; they need to be included too!
  • Not forgetting small appliances such as the kettle, toaster, iron and barista machine if you have one!

Child friendly holiday homes

Regularly welcome young families to your holiday home? You might have some of the following in your cottage:

  • Cots
  • Stair gates
  • Play equipment

Garage and garden items

Thinking outside of the home and into the garden shed, are you including the items that make that garden look as pristine as it does?

  • If not then factor in cover for items such as your lawnmower and garden tools.
  • Trampolines, and other play equipment would also form part of this section of your contents.
  • Patio and garden furniture
  • Ceramic planters, garden ornaments and statues, it all adds up

Those items you might not think of

When we think of contents we often think of personal items such as clothing, or other accessories such as our television. Here are a few you’ll need to allow for that might not immediately spring to mind:

  • Lighting, including lamps, and the light bulbs throughout your cottage.
  • The curtains and blinds in all of your rooms.
  • Carpets and floor coverings or rugs (commonly forgotten).

‘High risk’ items

If you have any particularly high value items within your holiday home, such as expensive pieces of art such as prints, paintings and sculptures, then these may need to be listed separately within your policy. Ask your insurer about these items when receiving your quote.

Once you’ve added up the replacement cost of the above, check it against your current sums insured and speak to your broker to increase your cover if necessary.

Boshers offer specialist holiday home insurance to owners across the UK. For more information on how a specialist insurer can help and support your holiday home business, please give us a call on 01237 429444.

For further information on UK holiday home insurance visit the website page most relevant to you:
N.B. This article is only an indication of the items that you should be considering when calculating your potential contents insurance. Please speak with us for further information or a quote for your holiday home insurance.

Insurance Premium Tax

Insurance Premium Tax In the Summer Budget, announced 8th July 2015, the Chancellor confirmed an increase of 3.5% in the standard rate of insurance Premium Tax (IPT). The increase is effective for new policies and renewals due on or after the 1st November 2015.

The standard rate of Insurance Premium Tax – the tax paid each time an insurance policy is purchased in the UK – is rising from 6% to 9.5%.

This change will affect the majority of insurance policies purchased by private individuals and small businesses for risks located in the UK.

Affected insurance policies with a start date after 31 October will have IPT charged at the new rate. This will increase the cost of a Holiday Home Insurance policy with a net premium of £500 by £17.50 bringing the total premium to £547.50 including Insurance Premium Tax at 9.5%.

If you are an existing Boshers holiday home insurance customer, with a policy start date before the 1st November 2015 and you need to make a change to your policy mid-term, you will continue to have the 6% rate applied until 1st March 2016. After this date, the rate will be 9.5%.

Higher rate IPT remains unchanged at 20% and applies to:

  • travel insurance
  • warranties for some mechanical and electrical goods

According to the Treasury the IPT increase will bring in an additional £8.1bn for the Treasury by 2021*. This was the second largest revenue raiser in the Summer Budget.

Insurance Premium Tax was first introduced to the UK in 1994. The rise on 1 November is the 4th increase in the standard rate since its introduction.

  • From 1 October 1994, a single rate of 2.5% was charged
  • 1 April 1997: increased to 4%
  • 1 July 1999: increased to 5%
  • 4 January 2011: increased to 6%
  • 1 November 2015: increased to 9.5%

*This is according to HMRC’s own figures summarising the impact of the move

The IPT increase is one of the chancellors more controversial revenue raising measures and the government has come under fire from the Association of British Insurers (ABI) who will continue to lobby to halt further increases. One of the justifications made by Mr Osbourne to justify the increase was that the UK’s insurance premium tax is well below that of other countries, for example Germany levies 19%.

Boshers offer specialist holiday home insurance to owners across the UK. For more information on how a specialist insurer can help and support your holiday home business, please give us a call on 01237 429444.

Richfords Fire and Flood

In this article we look closely at a holiday home insurance claim from the restoration companies perspective.

Holiday Home in Cornwall

Richfords Fire and Flood

The property is a terraced house split into 3 holiday flats, all of which had suffered a vertical Escape of Water (clean) in April. All three of the flats are used as holiday properties and had summer bookings, therefore the property needed to be restored as soon as possible to minimise the loss of rental income.

The Holiday Home Insurance Claim | Escape of Water causing a Vertical Flood

On the 7th of April a vertical flood was discovered as a result of a leaking pipe under the bath in the 2nd floor bathroom (Flat 3); Water escaped downwards in to 1st floor (Flat 2) and ground floor (Flat 1).

As a result of this leak there was a lot of work that needed to be carried out to restore the apartments, one of the first things being a check of the electrical circuit. This was to ensure that the electrics were safe and that water damage had not compromised them. If it had been found that they had been affected by the water, a temporary board would have been installed so that there was no further risk of electrocution or fire, as well as enabling the drying equipment to run safely and the occupants to have a safe electricity supply.

First response

The loss adjusting company first called Richfords in the morning of the 8th of April. Within two hours Richfords senior technician attended site with a fully equipped response vehicle and was immediately able to assess the incident.

Upon arrival our technician carried out a thorough survey of the property and found that the construction of the floors in the apartments could trap moisture from the incident leading to secondary damage.

Initial Concerns and Damage Limitation

The technician removed the wet and damaged carpets as soon as possible, to prevent any further damage to the flooring. Also trying to save the carpet so it can be cleaned and refitted rather than being left wet, which could result in the carpet being written off and having to be replaced. We also lifted the kitchens vinyl so save the cost of replacement. As this an uncommon kind of floor insulation, it would be a challenge, but one that we are capable of dealing with.

Standing water was extracted to prevent secondary damage from happening. The technician quickly installed state of the art dehumidifiers to reduce the humidity, followed by specialist injection drying. This technique is used to release trapped moisture and avoids the disruption and cost of removal of the insulation and screed.

Installation | Ground Floor Lounge and Kitchen

  • In both the Lounge and the Kitchen we Installed Kruger Air drying into the plasterboard to release any trapped moisture, once the walls had been dried we would then fill the holes in preparing them for redecoration.
  • Installing Kruger Air drying into the floating floor and filling of the holes once dry, to save the cost of replacement.
  • We also refitted the carpet and underlay once the building was dry and cleaned the carpet to save the cost of replacement.

First Floor Lounge and Kitchen

  • Unfortunately we were unable to save the Vinyl, Carpet.
  • In both the lounge and the kitchen we Installed Kruger Air injection drying system into the plasterboard to release any trapped moisture, once the walls had been dried we would then fill the holes in preparing them for redecoration.
  • Installing Kruger Air drying into the floating floor and filling of the holes once dry, to save the cost of replacement.
  • Removal of kitchen units/breakfast bar and bookcase. Lifting of existing chipboard floor plus two layers of plasterboard and insulation layer (approx 25sqm) and replace. Refit kitchen units, breakfast bar and bookcase.

Second Floor Bathroom

  • The floor had bowed therefore we had to remove the entire floor and replace it.

Conclusion

In total the drying project took 20 days. The quick response by the owner of the property in notifying the claim to their holiday home insurers resulted in Richfords being able to respond to this incident within hours.

The use of modern drying equipment and specialist injection drying resulted in a short project time scale and helped to keep the financial loss to a minimum. In addition the use of injection drying has reduced the possibility of trapped moisture causing further building issues in the future. All three of the holiday letting apartments were up and running again by the 25th May and occupied by paying guests.

Boshers offer specialist holiday home insurance to owners across the UK. For more information on how a specialist insurer can help and support your holiday home business, please give us a call on 01237 429444.

You may find the following holiday home insurance articles of interest:

For further information on UK holiday home insurance visit the website page most relevant to you:

Insurance for Holiday Cottage Complex

Insurance for Holiday Cottage ComplexAs a holiday cottage complex owner does the sound of teaming up with an intermediary specialising in insurance for holiday cottage complexes sound appealing? With more than 25 years experience of insuring properties just like yours, we’re here to help you.

What do we mean when we use the words ‘specialist insurance’? We devote our time to advising on insurance for holiday cottage complex owners and individual holiday homes across the country. We speak to owners each and every day; we understand what they want and what they need from their insurance provider, and from their insurance policy.

We believe our insurance helps and supports you when you need it the most; here are just a few examples of how our holiday complex insurance will do that for you…

Insurance for Holiday Cottage Complex Owners that includes £10m Public and Products Liability Cover

It stands to reason that the more cottages you own, the more visitors you’re likely to have during the year, and in particularly during those busy summer months.

It’s therefore vital that you have a sufficient amount of Public Liability cover.

Public liability insurance covers the legal liability of the policyholder for accidental bodily injury to third parties or damage to their property.

If for example, a visitor to one of your cottages sustained a serious injury as the result of an accident whilst staying with you, our insurance policy would cover you up to the sum of £10,000,000 in any single incident.

£10m Employers Liability Cover

Most holiday home complexes will employ people to work inside or outside of their properties, for example in the form of gardeners, maintenance and housekeeping staff for those all important changeovers.

If you do, it is a legal requirement for you to have Employers Liability insurance and this will cover you against injury or illness sustained in the course of their employment.

Remember, even if you are directing the work of self-employed contractors or employing friends to work on your complex during busier periods, you’ll still need this cover.

Accidental Damage

Sometimes accidents happen.  As we’ve already said, you’ll have a large number of guests staying with you each year, which can in turn make a mishap all the more likely.

Should a guest spill red wine on that wonderful new carpet you’ve laid, or cause damage to any of your properties as the result of an accident, Boshers will be able to cover you for the damage subject to the policy excess.

Theft or attempted theft, even when your cottage is occupied

A holiday is a time when most of us will let our guard down, and also spend a lot of time exploring, rather than inside a holiday home.  For this reason, holiday cottages can become targets for thieves, and despite the larger numbers of visitors on site at a holiday complex at any given time they are not immune to this.

We’re able to offer theft cover to complex owners, even when your cottages are occupied by paying guests.

Home Insurance too!

Want to have all of your insurances in one place? That’s not a problem; we’re also able to offer our complex owners the same high level of service and experience for their home insurance too.

Tailored and experienced

When you take out insurance with Boshers we’ll tailor the sums insured to make sure you have the right policy for your needs.  We’ll also talk you through all of the areas of cover we offer, along with why and when you may need them. We also understand that your cottage complex may have additional facilities such as hot tubs, swimming pool, a games room or pets corner to name but a few.

Additional guidance on insurance for holiday cottage complexes and quotes are available from the Boshers Holiday Home Insurance Team on 01237 429444.

For further information on UK holiday home insurance visit the website page most relevant to you:

Insurance for Listed Holiday Lets

Hucksteps Row, Rye, Sussex, Grade II Listed, Kent and Sussex Holiday Cottages

When we search for a holiday many of us will look to the nearest beach, others toward finding a secluded spot in the countryside, maybe even a combination of both that will keep our young family occupied for a full week.

No matter what you’re looking for, one thing you’ll never be short of in the United Kingdom is heritage. There are no fewer than 380,000 listed buildings on our shores, and with many of them now able to be used as holiday homes we take a look at the unique insurance requirements that come with owning your very own slice of history.

Specialist Insurance for Listed Holiday Lets 

As the owner of a listed property you’ll no doubt be familiar with the sometimes stringent guidelines and regulations surrounding your holiday home. For this reason we offer listed property owners a specialist and bespoke policy, understanding that because your holiday home is like no other, your insurance shouldn’t be either.

Here are just a few of the areas you’ll be covered for when you choose our insurance for listed holiday lets:

Archaeological Costs up to £250,000

Damage to a holiday home can be potentially catastrophic, particularly in lost bookings, expense and the stress of returning your property to its former glory.  With listed buildings this process can also be complex; you may require archaeological or rescue work to salvage original materials in order to perform the necessary restorations.

Our policy covers these costs for you, meaning you’ll have the support and understanding of Boshers when it comes to the requirements placed on you by local authorities.

20% of your sum insured to meet local council requirements

If a listed property is damaged the local council will often impose certain conditions upon the restoration of the property.  We know and understand this process, so our policy offers a further 20% of your buildings sum insured to cover the expense of meeting these requirements in the event your property is damaged as the result of an insured event, such as fire or flood.

Loss of rental income

If your holiday home does become uninhabitable as the result of something outside your control such as fire or flood it can have serious financial consequences.  Restoring a listed property will often take longer than a standard holiday home, meaning the potential loss of income can be even greater.

If the worst does happen our insurance Policy really is here to support you.

Our Loss of Income cover means you’ll not need to foot the bill for the potential loss of bookings and cancellations you have to make while you get your property ready to take guests again.

Experience tells us that whilst in an ideal world all bookings would be made early, for some a higher proportion will be taken at the last minute. We’ll be able to look at bookings taken for a similar period in previous years in order to make sure you get the right amount of cover for the losses you’re incurring.

Experience and Expertise

When you insure your listed property with Boshers you’ll not only benefit from more than 20 years of specialist holiday home insurance experience, you’ll also be teaming up with the UK’s leader in providing insurance for properties just like yours.

Our Policies are underwritten by Ecclesiastical, who insure more Grade I listed buildings than any other insurer, including 42 of the 43 cathedrals in the UK.

Together you can be sure you’ll get the perfect blend of holiday home and listed building experience, ensuring you have the cover that you need.

Boshers are specialist providers of Listed Holiday Home Insurance. For more information on how a specialist insurer can help and support your holiday home business, please give us a call on 01237 429444. 

Follow this link for posts similar to Insurance for Listed Holiday Lets with Heritage and other useful resources for holiday home owners.

You may also find the following post for Listed Holiday Let owners of interest:

Boshers specialist holiday home insurance webite on ipad

Boshers specialist holiday home insurance webite on ipadSpecialist is a word that is often used but one we take really seriously and to heart. We’ve been specialising in insurance for holiday letting properties for 25 years. With that amount of experience under our belt we understand the industry.

Speaking with holiday homeowners every day gives us the knowledge and understanding that allows us to ensure we have one of the most comprehensive specialist holiday home insurance policy wordings possible for you and your needs as a cottage owner.

How our Specialist Holiday Home Insurance Policy can help

Here are just a few ways our Specialist Holiday Home Insurance Policy can help cover you when you need it the most:

£5m public and products liability

With the volume of people visiting and staying in your holiday home it’s vital you have an adequate level of public liability insurance.

Public liability insurance covers the legal liability of the policyholder for accidental bodily injury to third parties or damage to their property.

For example, if you were held legally liable for an accident in your holiday home that caused injury to a guest or to some of their possessions, you would be covered under your public and products liability insurance.

£10m employer’s liability

If you employ people to work inside or outside of your holiday home, for example in the form of a gardener or a cleaner, you will need employers liability insurance.

This will cover you against injury or illness sustained in the course of their employment.

It is a legal requirement to display your employer’s liability Certificate of insurance; we’ll provide this for you when you take a policy out with us.

Loss of rental income

What would you do if something happened to your property that meant it were out of action for the busiest time of the year?  Would you be able to stomach the financial implications of the potential loss of income during those summer months?

If your holiday home becomes uninhabitable as the result of something outside your control such as flood or fire it can have serious financial consequences.

This insurance covers you for the potential loss of income you may suffer as a result of disruption or interruption caused by an insured event.

What this means is that should you lose trade then you’ll not have to pay the price of the loss of trade you suffer through cancellations and periods of not being able to accept bookings.

Legal expenses up to £100,000

If you have a dispute with an employee, supplier or guest the legal costs can quickly add up and even run out of your financial control.

Our legal expenses cover is there to protect your legal position on a range of employment or business disputes.  We will negotiate for your legal rights after an event that causes physical damage to your holiday home or to evict anyone in your property who does not have permission to be there.

Your legal rights will also be defended if an event arising from you letting your holiday home leads to you being prosecuted in a criminal court.

You’ll also benefit from a number of helpful helplines, which will give you guidance on areas such as commercial law, tax and online employment and business law.

Accidental Damage

Sometimes accidents happen; red wine ruins that new cream carpet, or a guest accidentally breaks a chair.  Our policy covers most accidental damage that can occur, subject to some exceptions that insurers generally consider to be uninsurable, such as damage caused by cleaning or the corruption of information on a computer.

This means that should your guest accidentally break something, you won’t be left with a large bill.

These are just a general overview of how our specialist Holiday Home insurance aims to support holiday home owners. We always encourage anyone looking for insurance to read their Policy document in order to fully understand the cover you have in place and also ensure that when you’re looking for quotes that you are comparing like for like cover.

For further information on UK holiday home insurance visit the website page most relevant to you:

For more information on how our specialist holiday home insurance could help cover your property please give our friendly team a call on 01237 429444. 

New addition to our specialist holiday home insurance policy – Legionellosis Liability Cover

iStock_000026201276MediumWe are pleased to announce that when our holiday homeowners next renew their specialist holiday home insurance policy they’ll be benefiting from even more cover. We will now be providing public and products liability cover as standard, which will indemnify owners against accidental bodily injury caused by Legionellosis starting at £250,000 in any one period of insurance. Legionellosis cover is a welcome addition to our already comprehensive holiday home insurance policy.

As specialists in holiday home insurance we understand the industry and the unique insurance requirements of your business. We’re committed to providing holiday let homeowners across the country with a range of cover that meets your needs.

If you’re not familiar with Legionelllosis and how it can affect your guests here’s some more information for you… 

What is Legionellosis and how do you get it?

Legionellosis is the collective term for a group of diseases caused by legionella bacteria. The best known and most serious of these is Legionnaires’ disease, which is a potentially fatal form of pneumonia. Whilst any of your guests could contract Legionnaires’ disease, certain groups of people visiting your holiday home will have increased levels of vulnerability.

These include:

  • People over the age of 45 years.
  • Smokers, heavy drinkers or those with impaired immune systems.
  • Individuals suffering from diabetes, heart, lung disease or other respiratory issues. 

The disease can not be passed from guest to guest as it is contracted by inhaling small water droplets suspended in the air, known as aerosols.  

Where will you find Legionella? 

Legionella bacteria are commonly found at low levels in natural water sources such as rivers, ponds and reservoirs, although it is unlikely someone will contract the disease in these conditions.

The risks of contraction are increased when the water is maintained at a temperature to encourage growth in the number of bacteria and where water may remain stored for a period of time.

In holiday homes the prime areas susceptible to infection will be hot and cold water systems, along with spa and hot tubs, where water may remain at a warm level and be present for a long period of time.

How do you prevent it? 

As a holiday homeowner you have a legal duty to ensure all water systems in your premises are properly operated and maintained to prevent Legionnaires’ disease or any other type of water-borne infection.  

The two most important factors for preventing an outbreak of Legionnaires’ disease are:

  • Temperature – cold water should be stored and distributed below 20ºC (68ºF) and hot water heated to above 60ºC (140ºF), distributed at 50ºC (122ºF) or higher. If there is a risk of scalding such as with bath or shower taps then a thermostatic mixer tap should be fitted.
  • Hygiene – the water should be kept free of any impurities and never allowed to stagnate (which is when water loses its freshness by lack of movement). Good housekeeping will reduce the risks, such as flushing out infrequently used shower heads and taps at least weekly and cleaning and de-scaling shower heads and hoses at least quarterly.

A qualified and competent professional should carry out all water works within your holiday home. You should keep documentation of when your system was last checked, along with schedules for regular maintenance and review. 

If your holiday home includes a swimming pool, spa pool or hot tub system we’ve written these more in-depth post on controlling risks such as Legionellosis:

The Health and Safety Executive have produced useful guidance on Legionella and Legionnaires’ disease.   

  • To read the Health and Safety Executives best practice advice on Legionella and Legionnaires’ disease click here

If you have any questions or queries regarding the insurance cover you have in place or if you require a quotation from a specialist for your holiday home insurance please give one of our experienced team a call on 01237 429444.

This article has been created as generic guidance for holiday home, cottage and holiday cottage complex owners and does not constitute legal or insurance advice. If you have any questions relating to health and safety management and the prevention of legionellosis at your holiday cottages you should take advice. 

Why choose Boshers for your holiday home insurance?

Holiday Home Front Door We spend every day talking to holiday homeowners. It’s what we do and as a specialist it gives us a unique insight into the industry and the insurance cover your holiday home really needs.

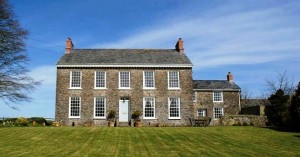
Whilst there’re many reasons to choose specialist Holiday Home insurance from Boshers, liability cover for paying guests being just one of them, here are three other ways our insurance Policy supports our holiday homeowners when they need it the most.

Full loss of rental income: Included as standard

What would you do if damage to your holiday home meant you were unable to let it during the busiest time of the year? 

If your holiday home becomes uninhabitable as the result of something outside your control such as fire or flood it can have serious financial consequences. With the average holiday home taking 80% of all bookings for the period of May to September the impact can be even greater if the incident falls during the busy summer months.

If the worst does happen our insurance Policy really is here to support you.

Our Loss of Income cover means you’ll not need to fit the bill for the potential loss of bookings and cancellations you have to make while restoring your holiday home to its former glory.

Experience tells us that whilst in an ideal world all bookings would be made early, for some a higher proportion will be taken at the last minute. We’ll be able to look at bookings taken for a similar period in previous years in order to make sure you get the right amount of cover for the losses you’re incurring.

We also know that things don’t happen over night and repairs can take time; our indemnity extends to two years, which is plenty of time to get you back on your feet.

Accidental Damage to Buildings or Contents

What would you do if a guest knocks a bottle of red wine onto your cream carpet meaning it needs to be replaced?

Whilst some wear and tear is inevitable for your holiday home, accidents that leave the property uninhabitable as a result can happen.

In these circumstances you’ll want to find the best possible solution in the shortest possible time so as to minimise potential disruption.

Our Holiday Home insurance Policy covers accidental damage to both the buildings and the contents of your holiday home.  This means that if there is significant damage caused to your property as the result of an accident or even malicious damage by paying guests we’ll support you in getting it sorted.

Theft or Attempted Theft

What would you do if your guests went to the beach for the day and left a window open, resulting in the theft of property from your holiday home?

Guests will often spend a large amount of their time outside of your property, hopefully enjoying the great British countryside or coastline bathed in glorious sunshine. This means that your holiday home will be empty for many hours during the day, making it a potential target for opportunistic thefts.

As many holiday home owners live away from their property it can be difficult to police how seriously your guests treat the security of your holiday home; it can be tempting for example to leave a window open during the day to avoid returning to a stuffy and intolerably hot living room.

If you’re holiday home is the victim of a theft or damaged as the result of an attempted theft we’ll again be able to cover you for the losses you incur.

Always read the Policy

These are just a general overview of how our specialist Holiday Home insurance aims to support holiday home owners. We always encourage anyone looking for insurance to read their Policy document in order to fully understand the cover you have in place and also ensure that when you’re looking for quotes that you are comparing like for like cover.

For further information or if you require a quotation from a specialist for your holiday home insurance call our team on 01237 429444.

Home with holiday let annexe

Holiday Let Insurance for your annexe

In this post we explore the subject of holiday let insurance for your annexe. It is becoming more and more common in popular rural and coastal self-catering holiday areas for owners of larger properties and empty nester’s to sub-divide their homes and let an annexe to guests holidaying in the area. In doing so, due consideration should be paid to the relevant planning and building regulations as well as the laws applicable to you as a landlord. Letting your annexe to guests can be financially rewarding although as with running any business it does have it’s risks. For your peace of mind you’ll want appropriate holiday let insurance for your annexe.

Holiday Let Insurance for your annexe

By taking advice on holiday let insurance for your annexe from a qualified adviser such as those in the Boshers holiday home insurance team, you will end up with building and contents cover without compromise and tailored to your individual needs. For a home owner with a self-contained holiday letting annexe or self contained detached holiday cottage in the grounds Boshers would look to provide you with comprehensive home insurance cover to meet your personal needs and running alongside a holiday home insurance policy to cover the contents of your holiday let together with cover for your liabilities as a holiday let owner and protection for loss of rental income in the event that you were to suffer an insured peril. Placing insurance for both your home and holiday let with the same insurer will save potential conflicts in the event of a claim. Should your home and annexe have an interconnecting door, you will be required to ensure that the door is fitted with a 5 lever mortice deadlock and kept locked so that guests do not have access to your home. For advice on holiday let Insurance for your annexe call our friendly team of holiday home insurance advisers on 01237 429444.

Holiday home annexe owners will also find the links below of interest:

For Self-Catering holiday cottage owners in Scotland, the Scottish Government has produced the following:

You may also find the following posts for holiday home owners of interest:

Follow this link for posts similar to Holiday Let Insurance for your annexe other useful resources for holiday home owners

For further information on UK holiday home insurance visit the website page most relevant to you: