
 If your holiday home were to be significantly damaged by fire or flood, do you know how much it would cost to rebuild and restore it to its former glory? If the answer to our question is ‘no’ then you may have the wrong level of buildings insurance in place.
While we hope the worst will never happen, there are more than 37,000 house fires in the UK every year. That’s in excess of 100 every day. While thousands of homes have also been affected by flooding or storm damage in the increasingly extreme weather patterns that have hit our shores in recent years.
In these circumstances, understanding and knowing the true cost of rebuilding your home or holiday home is key. By being informed you can ensure you have the right level of buildings insurance in place.
What does a rebuild cost represent?
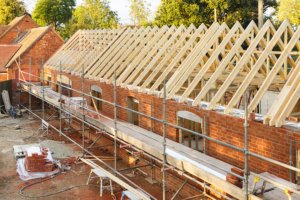
The rebuild cost represents the costs you’ll need to cover in order to restore your property; you’ll need to pay the builders, pay for scaffolding and materials, cover the costs of new windows, etc.
Recent research from RebuildCostASSESSMENT.com has found that when setting their buildings sum insured:
- over a third of policyholders are using the ‘market value’ of their property; and
- one in five ‘simply guess’.
Thus leaving them potentially out of pocket if they’ve underestimated this figure and the worst happens, or overpaying on their insurance premium if they’ve overstated the costs of rebuilding.
It is a common misconception that buildings insurance relates to the current market value of the property, rather than the cost of rebuilding it, but in reality these figures can often be far apart.
What do you need to consider when calculating your rebuild cost?
It can be difficult to calculate the exact costs of rebuilding your property, but you’ll need to think about all of the following:
- The building cost of reinstating your property – this isn’t just limited to the walls of your holiday home, and can include items such as swimming pools, paths, drives, patios, and other things that you might not think about, such as satellite dishes, fences and landscaping.
- The cost of replacing fixtures and fittings – for example, do you have built-in wardrobes or specialist light fittings that would cost significant sums to replace or restore?
- Will debris need to be removed from the site? Will you need to hire skips? How much will you be charged for removing waste from the building site?
- What will be the cost of complying with Local Authority Buildings Regulations or other statutory requirements?
- Professional fees – to get your property back to where it was before the incident you’ll likely need to consult with engineers, architects and surveyors. Their fees will also need to be included in your calculations.
How can you make sure that your rebuild cost is correct?
There are a number of ways and methods you can use to calculate the value of your holiday home. These range from using the ABI online calculator if your holiday home is of a standard construction (http://abi.bcis.co.uk/) through to instructing a RICS qualified Chartered Surveyor (a method used by only 5% of respondents to the RebuildCostASSESSMENT.com survey).
Take the hassle out of setting your rebuild cost with a desktop survey
The good news is that we have teamed up with RebuildCostASSESSMENT.com to offer our home and holiday home insurance clients a discount off of their cost effective desk top surveys.
For more information on your options please take a read of our blog post:
Boshers offer specialist holiday home insurance to owners across the UK. Need an insurance quote for your holiday let? Give us a call on 01237 429444.


 Dog friendly holiday home insurance is well worth considering if you offer pet friendly self-catering accommodation. The dog-friendly tourism market is one that’s grown exponentially over the past decade. This isn’t surprising considering that a staggering one in four UK households has a dog to call their own.

 A question that all holiday homeowners will have asked themselves, or perhaps wonder when their insurance is up for renewal. How much should I be paying and is it value for money? So how much should your

 As specialists in

 In the 2016 Autumn Statement, the Chancellor confirmed an increase of 2.0% in the standard rate of Insurance Premium Tax (IPT). [The tax paid each time an insurance policy is purchased in the UK]. The increase is effective for new policies and renewals due on or after the 1st June 2017.

 Whether you’ve recently bought a holiday home or survived your 30th season, it’s equally important to have the right insurance. As

 Accidents happen, and whilst

 When you’re renewing your holiday let property insurance there are a few points you need to bear in mind. As you’re aware, a holiday let is very different to your average home, so having

 For many holiday homeowners across the UK 2016 was a great year. For some it may have even been record breaking. As we approach the new year with optimism and await the January influx of Easter and summer bookings, have you considered what you’d do if your holiday home became unavailable for all of those guests to stay in?